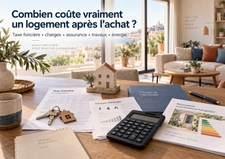
Property Tax, Service Charges, Renovation Costs: What Does a Home Really Cost After You Buy It?
Property tax, condominium charges, insurance, energy bills, maintenance and renovation costs… Discover the real cost of owning a home after purchase and how to avoid unpleasant surprises.
Buying an apartment or a house is not just about the asking price in the listing, or even the monthly mortgage payment. Once you become a homeowner, a range of recurring and occasional expenses must be added to your budget.
This is especially timely, as 2026 property tax notices are currently being issued to owners in France. But beyond property tax alone, one key question deserves attention before buying:
How much does a property really cost once you own it?
Property tax: a cost to review before making an offer
Property tax is one of the first expenses to include in your annual ownership budget.
Its amount depends on several factors, including the cadastral rental value of the property and the rates set by local authorities. As a result, two homes with a similar purchase price may carry very different annual property tax bills depending on their location and characteristics.
For buyers, one of the best habits is to ask the seller for the latest property tax notice as soon as the purchase becomes serious.
It is also important not to confuse property tax with household waste collection charges, which may appear on the same tax notice.
Condominium charges: look beyond the amount and understand what is included
For apartment buyers, condominium or service charges are often the second major recurring cost to review.
These charges may cover common area maintenance, the property manager, building insurance, lifts, green spaces, concierge services, and in some buildings, collective heating or water.
A high amount does not automatically mean poor management. For example, €300 per month including heating and water does not mean the same thing as €300 covering only routine building maintenance.
Before buying, it is therefore essential to review not only the annual amount of the charges, but also what they include and how they have evolved over time.
This is where supporting documents matter. They help buyers understand what the current owner has paid in recent years and whether any exceptional expenses have already occurred.
Building works: the expense that can completely change your budget
This is often where the biggest financial surprises are hidden.
Façade renovation, roof repairs, replacement of a collective boiler, terrace waterproofing, lift replacement or energy-efficiency upgrades can represent several thousand euros — and sometimes much more — per co-owner.
That is why it is essential to read the latest minutes from condominium meetings before committing to a purchase. A property may seem attractive and fairly priced, but become much less appealing if major works are about to be voted on or carried out.
On the other hand, if the façade, roof, common areas or building systems have recently been renovated, this can be a real advantage and a sign of better cost control in the years ahead.
A house may have no condominium charges — but that does not mean lower ownership costs
A detached house can appear simpler because there are no service charges or co-ownership rules.
In reality, the owner bears alone the expenses that would otherwise be shared in an apartment building: roof, façade, heating system or heat pump, gate, garden, pool, drainage or septic system, and general upkeep of the property.
It is therefore wise to build an annual maintenance reserve into your budget, even if the house is in excellent condition at the time of purchase.
Insurance, energy and maintenance: the smaller costs that quickly add up
In addition to property tax and service charges, homeowners also face other ongoing expenses: home insurance, electricity or gas bills, water when not included in charges, servicing of a boiler or air-conditioning system, small repairs, replacing appliances, and various subscriptions linked to the property.
Taken individually, these amounts may seem manageable. Added together over twelve months, however, they can represent several hundred euros per month.
Let us take a very simple example. An apartment with:
- €250 per month in service charges
- €1,500 per year in property tax
- €300 per year in home insurance
already represents€4,800 per year, or €400 per month, before even including electricity, possible repairs or mortgage repayments.
In other words, the purchase price tells only part of the story.
Energy performance has also become a financial issue
A property’s energy rating is no longer just an indication of future utility bills.
It can affect day-to-day comfort, the cost of future renovation work, and, for landlords, even the ability to legally rent out the property.
A lower-priced home with poor energy performance may appear attractive at first glance, but that price should always be assessed in light of the possible renovation costs required in the coming years.
This is especially true for older apartments, small city properties and homes where buyers are already trying to balance purchase price, monthly payments and future works.
Before buying, calculate a true “owner’s budget”
When most people search for a property, they think in terms of:
purchase price + notary fees + mortgage payment
A more realistic calculation would include:
- property tax
- condominium or service charges
- home insurance
- energy costs
- ongoing maintenance
- renovation reserve
- any works already identified in the building or the house
This broader approach often changes how two properties are compared.
A slightly more expensive apartment in a well-maintained building, with controlled charges and major works already completed, may ultimately prove more economical over ten years than a cheaper property requiring significant spending shortly after purchase.
The true price of a property is not limited to its price per square metre
In Paris, Nice, the French Riviera and elsewhere, the price per square metre remains a useful benchmark. But it should never be the only factor in a buying decision.
The condition of the building, annual property tax, energy performance, service charges and future expenses all play a role in the real value and real cost of a home.
Buying at the right price also means understanding what it will cost to own, maintain and finance the property over time.
That is precisely the value of a comprehensive real estate analysis: not just looking at how much a property costs today, but at what it will truly cost tomorrow.